Fintech Solutions for Small Businesses, NBFCs and Chit Funds in India
We build loan management, chit fund, KYC, payments and GST billing software for small NBFCs, microfinance institutions, chit fund companies, co-operative societies and growing shops across India. Our team works from Tiruppur, Tamil Nadu, and every project has a fixed written quote.
Big core banking and lending vendors are priced for banks. Cheap apps are built for everyone and fit no one in particular. Small lenders and businesses that handle real money need something in between: software shaped around their products, from a registered team they can visit, at a price published on this site.
Where a ready-made product would serve you better, we will say so.
Who we build fintech software for
Small NBFCs and gold loan companies
Lenders with a few branches who have outgrown Excel or an ageing desktop package, and need loan management and loan servicing software with EMI schedules, overdue tracking, gold loan valuation and auction records.
Microfinance institutions
MFIs and group lenders with field officers, centre meetings and weekly collections, who need microfinance software and a collection app that works on patchy mobile networks.
Chit fund companies
Registered chit companies running many groups, who want auctions, dividend and commission, agent collections and a chit fund app for subscribers in one system.
Co-operative societies and credit societies
Societies handling member deposits, loans and dividends, who need clear member ledgers and reports for their auditors and annual meetings.
Retailers who need GST billing
Shops, supermarkets, jewellers, pharmacies and distributors who need GST invoices, e-invoice and e-way bills, UPI collection and clean exports for their CA.
Small businesses adding payments
Service businesses, schools, clinics and online sellers who want UPI payment integration, payment links, subscriptions and automatic reconciliation.
Fintech products and solutions
Each page covers features, process, timeline, published prices and FAQs. Most lenders start with one piece and add the rest over time.
Loan Management Software
Origination, EMI schedules, field collections and overdue tracking for NBFCs, MFIs, societies and gold-loan lenders.
Chit Fund Management Software
Groups, auctions, dividend and commission, UPI collections, agent app and ledgers for registered chit fund companies.
KYC and eKYC Integration
Aadhaar eKYC via licensed partners, DigiLocker, PAN, CKYC, Video KYC, penny drop, face match and OCR in one onboarding flow.
Account Aggregator Integration
FIU-side AA integration: consent flows, bank statement and investment data fetch, parsing and underwriting insights.
Payment Gateway Integration Services
Razorpay, Cashfree, PayU, PhonePe, Stripe and PayPal integrations with UPI, subscriptions, split payouts, webhooks, refunds and reconciliation.
POS and GST Billing Software
GST billing and POS software for retail, restaurants, supermarkets and pharmacies, customised from our OverseePOS product.
GST Billing Software
GST invoices, e-invoice IRN and QR, e-way bills, GSTR-1 and Tally export for shops, traders and distributors.
Jewellery Billing Software
Daily metal rate, weight, purity, making and wastage, old gold exchange, HUID and GST invoices for jewellery shops.
Pharmacy Billing Software
Batch and expiry, Schedule H and H1 register, prescriptions, GST bills and supplier returns for medical shops.
Accounting Software Development
GST-ready invoicing, bank reconciliation, multi-currency billing and ERP-lite tools that sync with Tally, Zoho, QuickBooks or Xero.
WhatsApp Business API Integration
Order updates, payment reminders, catalogues and team inboxes on the official WhatsApp Business API, connected to your CRM, ERP or store.
AI Workflow Automation and AI Agent Development
Invoice and PO extraction, email and WhatsApp triage, and AI agents that update Tally, Zoho, CRMs and ERPs, with human review built in.
Fintech Software Development
Payment gateway and UPI integration, lending systems, wallets, eKYC and fintech MVPs built with audit-ready foundations.
How we compare with the alternatives
By category, not by name. Every option on this table is the right answer for someone. Here is where each one fits.
Swipe sideways to see every column.
| RED SAG | Large fintech and core banking vendors | Off-the-shelf SaaS | Freelancers | |
|---|---|---|---|---|
| Price level | Published price bands. Loan management from ₹1.75 lakh, chit fund software from ₹1.25 lakh | Highest. Licence, implementation and yearly maintenance fees, often priced for banks and large NBFCs | Lowest to start. Monthly fee per user, branch or loan, which grows as you grow | Often the lowest quote. The real cost shows up if the work stalls or has to be redone |
| Set-up time | Weeks for a focused first version, a few months for a full platform, delivered in milestones | Months. Long implementation projects are normal | Fastest. Days to weeks once your data is ready | Depends on one person’s availability |
| Customisation | Built around your products, rules and collection process | Configurable within the product. Custom changes are possible but expensive and slow | Settings only. The vendor decides the roadmap | Anything, if the person has the skills |
| Who owns the code and data | You own the code and data of custom work once it is paid for | The vendor owns the code. You licence it | The vendor owns the code. Check how you can export your data | Depends on the contract, and is often left unclear |
| Support | The same team that built it. Reply within one working day, with monthly support plans | Formal SLAs and large support desks, through ticket queues | Shared help desk for all customers | One person. Holidays, illness or a new job stop everything |
| Certifications and scale | Small team. No ISO 27001, SOC 2 or PCI DSS certification | Usually certified, with bank references and large teams | Varies by vendor. Some are certified | Rarely |
| Best fit | Small lenders, chit funds, co-ops and SMBs that need software shaped to their process on a small-business budget | Banks and larger regulated lenders that need certified vendors and scale | Lenders and shops with standard needs who want to start quickly | Small, clearly defined add-ons with close supervision |
General patterns, not claims about any particular company. Individual vendors, products and freelancers vary.
Choose SaaS when it already fits
If a ready-made loan, chit fund or billing product handles your work as it is, buy it. It is quicker and cheaper in the first year. We will tell you so on the first call.
Choose a large vendor when you need certification
If your board, investors or partner bank require an ISO 27001 or SOC 2 certified vendor, or you run hundreds of branches, a large core banking or lending vendor is the safer choice.
Choose a freelancer for small, supervised jobs
A single report, a plugin or a small integration can be fine with a good freelancer, as long as you hold the code and credentials yourself.
Choose us for the space in between
When SaaS does not fit, large vendors are out of budget, and the software handles real money, a registered team with fixed quotes and code ownership is a sensible middle path.
Deciding between a package and a build? Read custom fintech software vs off-the-shelf. Choosing a payment gateway? See Razorpay vs Cashfree vs PayU.
Built to support the rules you work under
We design software around the rules that apply to Indian lenders, chit funds and businesses. We build to support them; your compliance officer, CA or legal adviser confirms that your setup meets them.
RBI digital lending rules
Key fact statements with the all-in cost, disbursal and repayment directly between the borrower and the lender’s account, the cooling-off period, grievance officer details, and consent before collecting borrower data. We build the screens, records and audit trail these call for.
KYC, CKYC and Video KYC
PAN and bank account checks, Aadhaar-based e-KYC or offline XML through licensed partners, CKYC search and upload, and Video KYC journeys, with records kept as your KYC policy requires.
Account Aggregator framework
Consent requests through an RBI-licensed Account Aggregator, fetching bank statements and other financial data as a Financial Information User, and handling consent expiry and revocation. Sahamati, the industry alliance, runs the ecosystem registries and certification, and we handle the technical preparation for it.
Chit Funds Act, 1982 and state rules
Group-wise subscriber registers, auction minutes, dividend and commission calculations and accounts, set up to match your state’s rules and your registrar’s practice.
GST and e-invoicing
GST invoices, credit notes, e-invoice IRN and QR code through a GST Suvidha Provider, e-way bills and GSTR-1 exports for your CA.
DPDP Act, 2023
Clear consent and notices, collecting only the data a purpose needs, access controls, deletion when data is no longer needed, and a way for customers to exercise their rights, in line with the Act and its rules as they apply to you.
Not legal advice. Regulators update directions and limits often. We make no claim that any software is “compliant” on its own. Our fintech compliance guide explains what a development team builds and what stays with you.
AI that saves staff time, with people in charge
AI is useful in a small lender’s back office, as long as it assists your staff rather than replacing their judgement.
Reading KYC documents and bank statements
AI reads PAN cards, address proofs, salary slips and bank statement PDFs and fills the form for your staff, flagging anything it is unsure of. A person checks the result before it is used for any decision.
Collection reminders on WhatsApp
Polite, pre-approved WhatsApp reminders before and after each due date, with a UPI payment link, sent only to customers who have opted in. Replies such as “paid yesterday” are routed to a staff member, not answered by a bot guessing.
Reconciliation
Matching UPI, gateway and bank settlement lines against receipts and instalments every day. Clear matches are posted for approval, and anything unmatched goes to a person with the likely reasons listed.
Human approval and an audit trail
AI suggests and people decide. Every suggestion, who approved or changed it, and when, is logged. AI does not approve or reject loans: credit decisions follow the rules in your credit policy, and you can switch any AI step off.
What fintech software costs
Starting prices for each solution, from our published price list. Open any line for the full bands. Your fixed quote depends on scope, integrations and timeline.
- Loan Management SoftwareLoan servicing system for a small lenderfrom₹1.75 lakh≈ $2,700
- Chit Fund Management SoftwareChit software for a single branchfrom₹1.25 lakh≈ $1,800
- KYC and eKYC IntegrationKYC API integrationfrom₹60,000≈ $900
- Account Aggregator IntegrationAA consent and data fetch integrationfrom₹1.25 lakh≈ $1,800
- Payment Gateway Integration ServicesSingle gateway checkoutfrom₹15,000≈ $200
- POS and GST Billing SoftwareOverseePOS with light customisationfrom₹25,000≈ $400
- GST Billing SoftwareGST billing for a single shopfrom₹25,000≈ $400
- Jewellery Billing SoftwareJewellery billing for a single shopfrom₹35,000≈ $550
- Pharmacy Billing SoftwarePharmacy billing for a single storefrom₹25,000≈ $400
- Accounting Software DevelopmentIntegration or automationfrom₹60,000≈ $900
- WhatsApp Business API IntegrationNotifications setupfrom₹20,000≈ $300
- AI Workflow Automation and AI Agent DevelopmentSingle workflow automationfrom₹60,000≈ $900
- Fintech Software DevelopmentPayment or KYC integrationfrom₹90,000≈ $1,350
Starting prices for the smallest sensible version of each product, before any applicable taxes. Open any line for the full price bands and what each one includes.
Fixed quotes, milestones and your code
- 01
Reply within one working day
A developer or project lead reads your message and replies with first questions and, where possible, a rough budget.
- 02
NDA and discovery call
We sign an NDA on request, then walk through your products, users, integrations and compliance constraints on a video call or at your office.
- 03
Written fixed-price quote
Scope, what is out of scope, timeline and a milestone payment schedule, in writing. Where scope is unclear we say so and suggest a short paid discovery.
- 04
Demos every 1–2 weeks
You see working software on a staging link, not slides, and give feedback while changes are still cheap.
- 05
Handover and support
Source code, credentials and documentation are handed over, followed by a bug-fix period and an optional support plan.
Read the full delivery process, our engagement models and how we handle security.
A real team, in a real office
These are photos of our own office in Tiruppur, not stock images. When you hire RED SAG you are working with a registered company and a team you can visit, call or meet on video, so you always know who is building your software and where to find them.
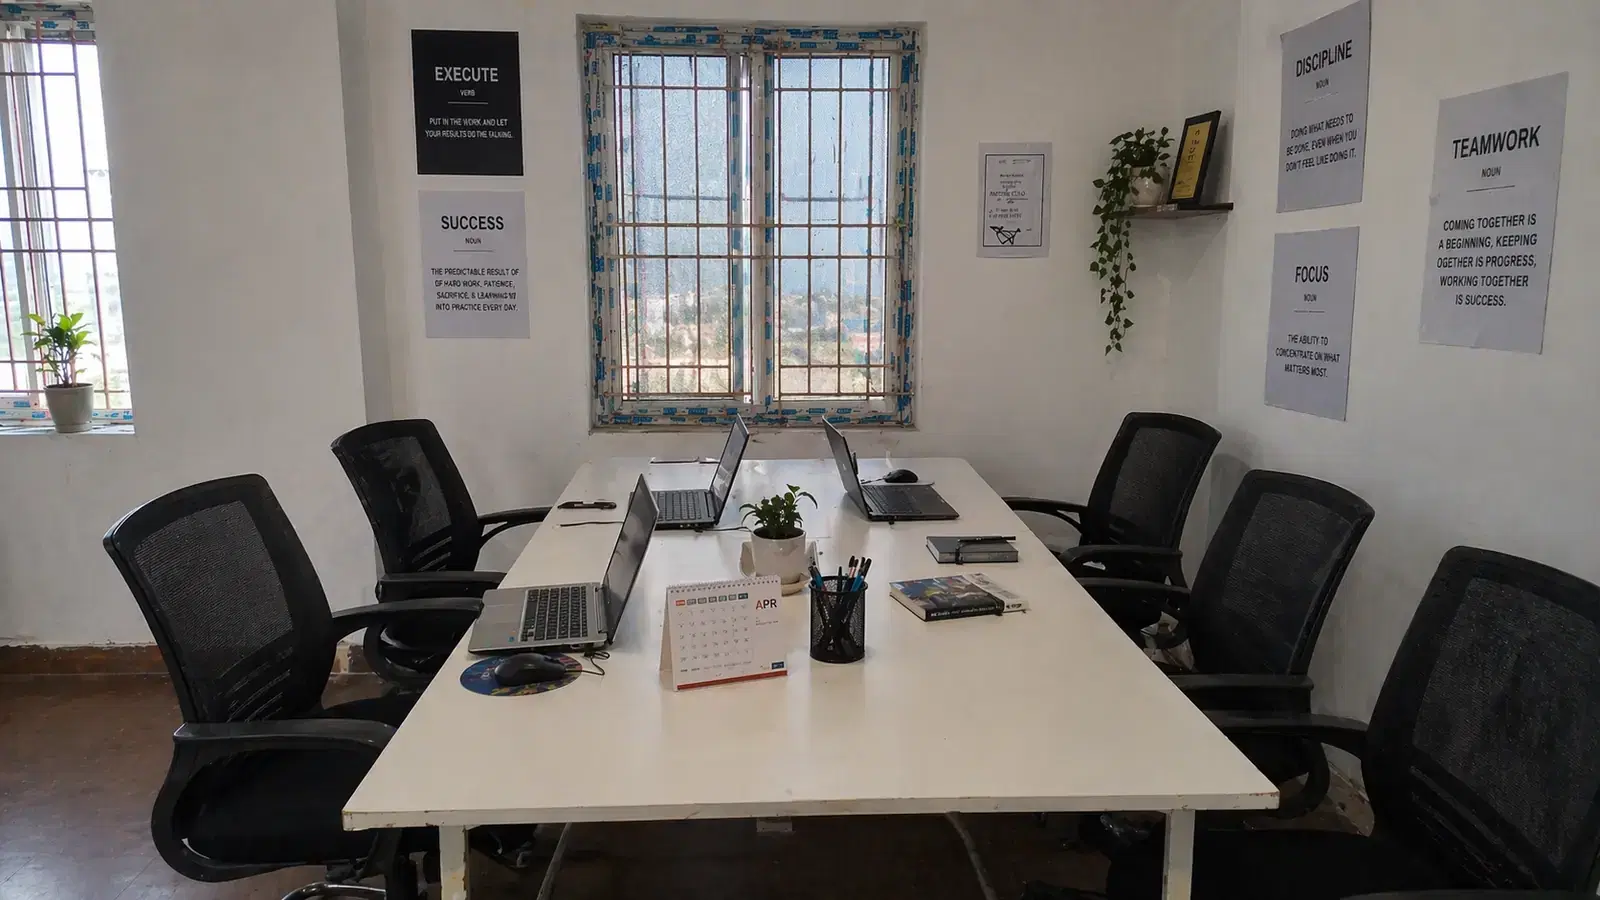
Where your project is built — our office in Arulpuram, Tiruppur 
The entrance: look for the red RED SAG board 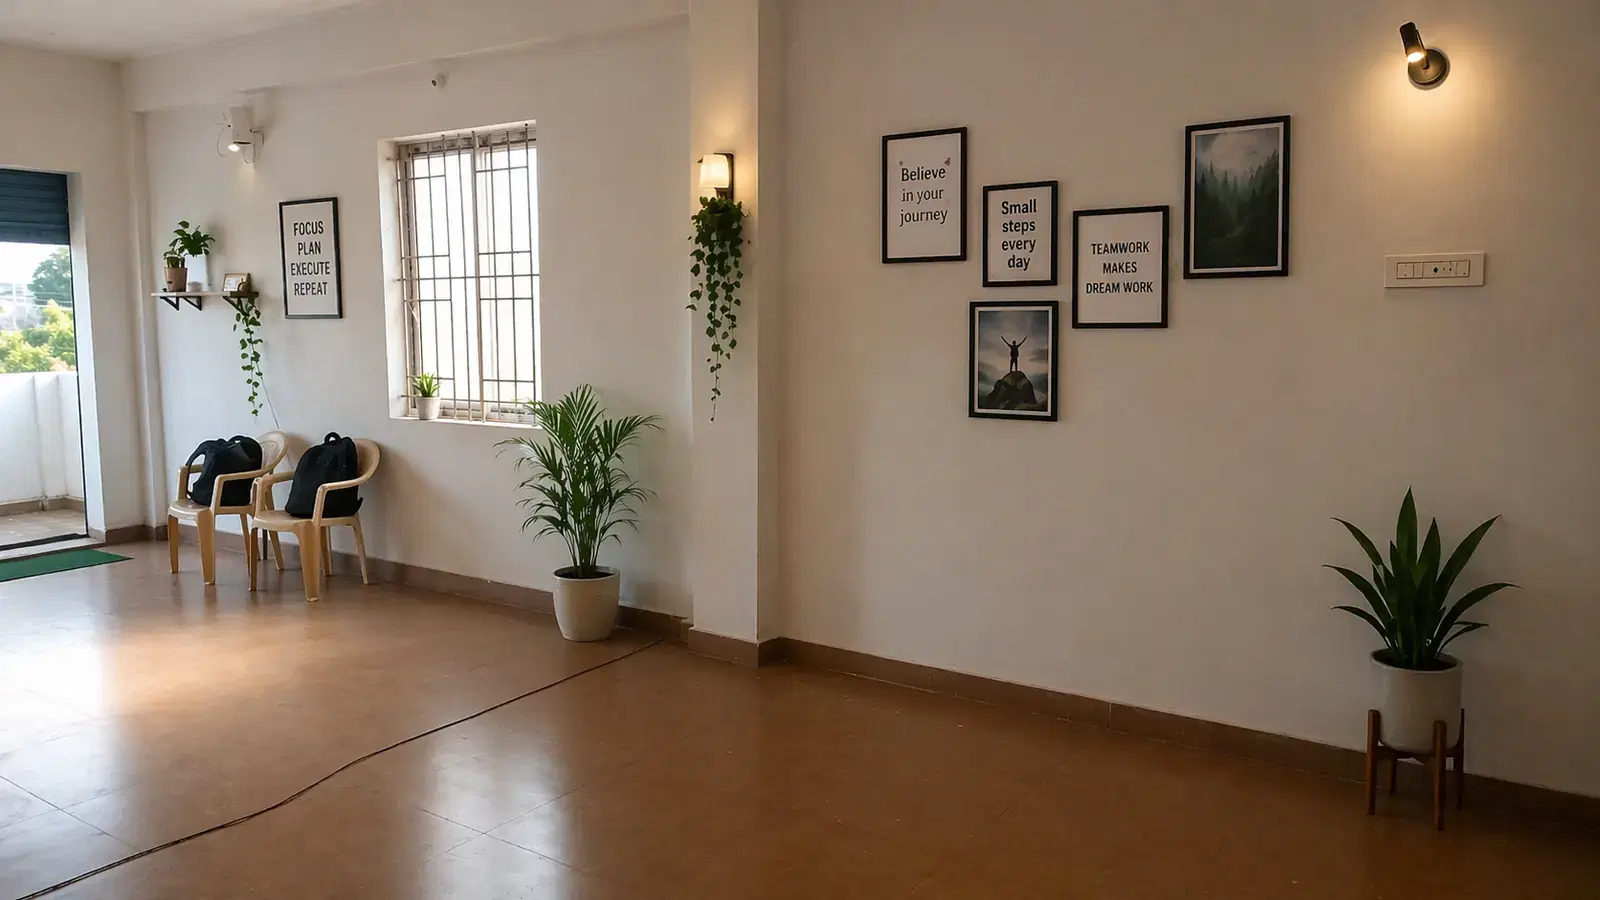
Inside the office: the common area on our floor 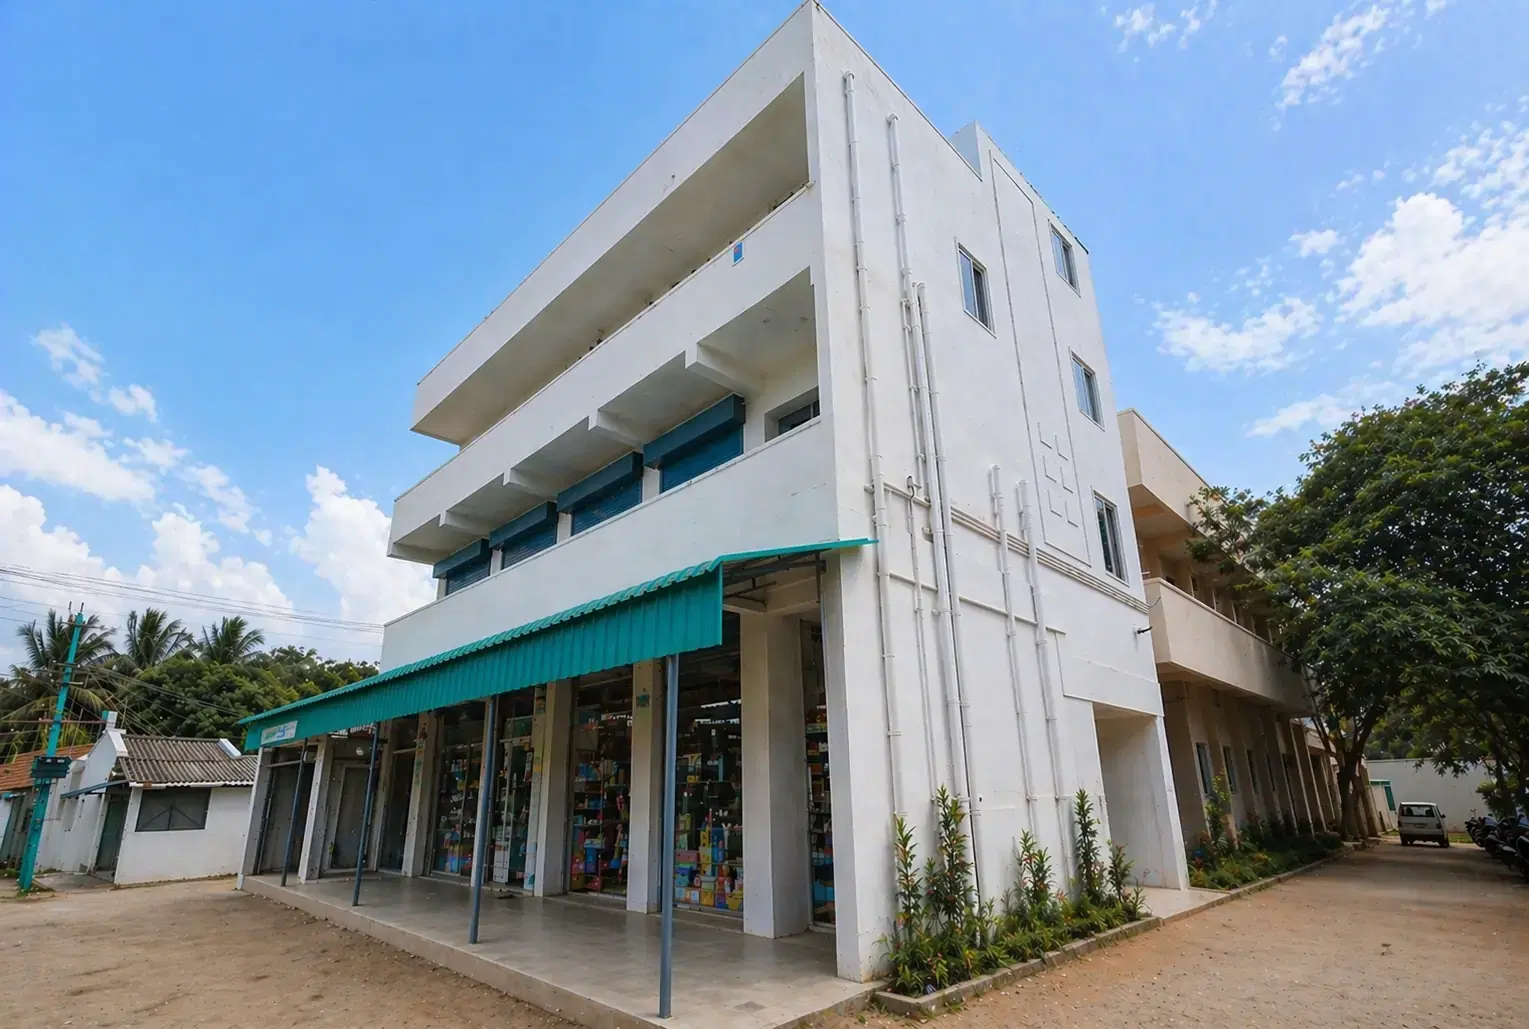
Our building in Arulpuram — you are welcome to visit
Why this matters when you choose a developer
- You can meet the people who build your software, in person or on a video call from this office.
- We are a registered business with a real address, not an anonymous freelancer who can disappear mid-project.
- Contracts, invoices and support come from the same company and the same team, year after year.
- Address
- RED SAG Fintech Solutions, Arulpuram, Tiruppur, Tamil Nadu, India
Open in Google Maps(opens in a new tab) - Office hours
- Mon–Fri, 9 AM–6 PM IST
- Phone
- +91 63830 04791
- info@red-sag.com
- Business registration
- Udyam-registered MSME: UDYAM-TN-28-0186267
Frequently asked questions
What fintech solutions does RED SAG build?
Loan management and loan servicing software, microfinance and gold loan systems, chit fund software and apps, KYC and e-KYC integration, Account Aggregator integration, UPI and payment gateway integration, GST billing and POS, accounting software, WhatsApp reminders and AI workflow automation. Each has its own page with features and published prices.
Why focus on small lenders and small businesses?
Large lending and core banking vendors are built and priced for banks and big NBFCs. Low-cost SaaS works when your needs are standard. Small NBFCs, MFIs, chit funds, co-ops and growing shops often fall between the two, and that is the gap we work in.
How much does fintech software cost for a small lender?
Our loan management software starts at ₹1.75 lakh and chit fund software at ₹1.25 lakh for a focused first version. Integrations such as payment gateways start at ₹15,000. Every project gets a fixed written quote after a scoping call, and all our price bands are published.
Is your software RBI compliant?
We build software to support the rules that apply to you, such as RBI digital lending rules, KYC directions and the DPDP Act, with disclosures, consent records and audit trails. Compliance itself belongs to your organisation: your compliance officer, CA or legal adviser confirms that the setup meets your obligations. We do not give legal advice.
Do you build NBFC software and microfinance software?
Yes. Our loan management software covers NBFC products such as personal, vehicle, MSME and gold loans, and microfinance group lending with centre meetings and field collections. It is built around your products rather than a fixed template.
Can you integrate KYC, UPI and Account Aggregator APIs?
Yes. We integrate KYC providers for PAN, bank account and Aadhaar-based checks, CKYC and Video KYC, UPI payment integration and UPI AutoPay or eNACH mandates through gateways such as Razorpay, Cashfree and PayU, and Account Aggregator APIs for consent-based bank statement data.
Should we buy SaaS or build custom software?
If a ready-made product fits the way you work, buy it. Build when your process is different, subscription costs grow faster than your business, or you need to own the code and data. Many lenders combine the two. Our build-versus-buy comparison explains the trade-offs.
Who owns the code and the data?
Your data is always yours. For custom work, the intellectual property is assigned to you once the related invoices are paid, and you receive the full source code and documentation. Where we build on one of our own products, the licence terms are agreed in writing before work starts.
How do you use AI in fintech software?
For reading documents such as KYC proofs and bank statements, sending collection reminders on WhatsApp and matching payments during reconciliation. A person approves every AI suggestion that affects a customer or the books, and every step is logged. AI does not approve or reject loans; credit decisions follow your credit policy and your approvers.
How can we check RED SAG before paying?
We are a Udyam-registered business (UDYAM-TN-28-0186267) with an office in Arulpuram, Tiruppur, that you can visit or see on a video call. You can verify our registration on the government portal, ask to speak to a past client, and start with a small paid pilot. Our why RED SAG page lists these checks.
Check us before you decide
Running a small lender or growing business? Let's talk.
Share a few lines about your idea. We reply within one working day with questions, a rough budget and the next step, with no obligation.
- Reply within one working day
- Fixed-price quote, no obligation
- You own the code and the data
“Great service”
Need a detailed estimate? Request a full quote